WHAT THIS GUIDE COVERS
- The 30% deposit is only half the story
- How much will a Spanish bank typically finance?
- The deposit does not include acquisition costs
- Acquisition taxes depend on the property and the region
- The bank’s valuation can change the numbers
- Every lender assesses international buyers differently
- Purchasing through a company requires different planning
- High-net-worth clients are not always assessed on income alone
- Think in terms of liquidity, not simply the deposit
- Our perspective
The 30% deposit is only half the story
One of the first questions international buyers ask is:
“How much deposit will I need to buy a property in Spain?”
The answer is often simplified to 30%.
While this is a useful starting point, it rarely reflects the total amount of capital required to complete a purchase.
For most non-resident buyers, the more relevant question is not how much deposit is required, but how much liquidity should be available before making an offer. The difference can be substantial.
How much will a Spanish bank typically finance?
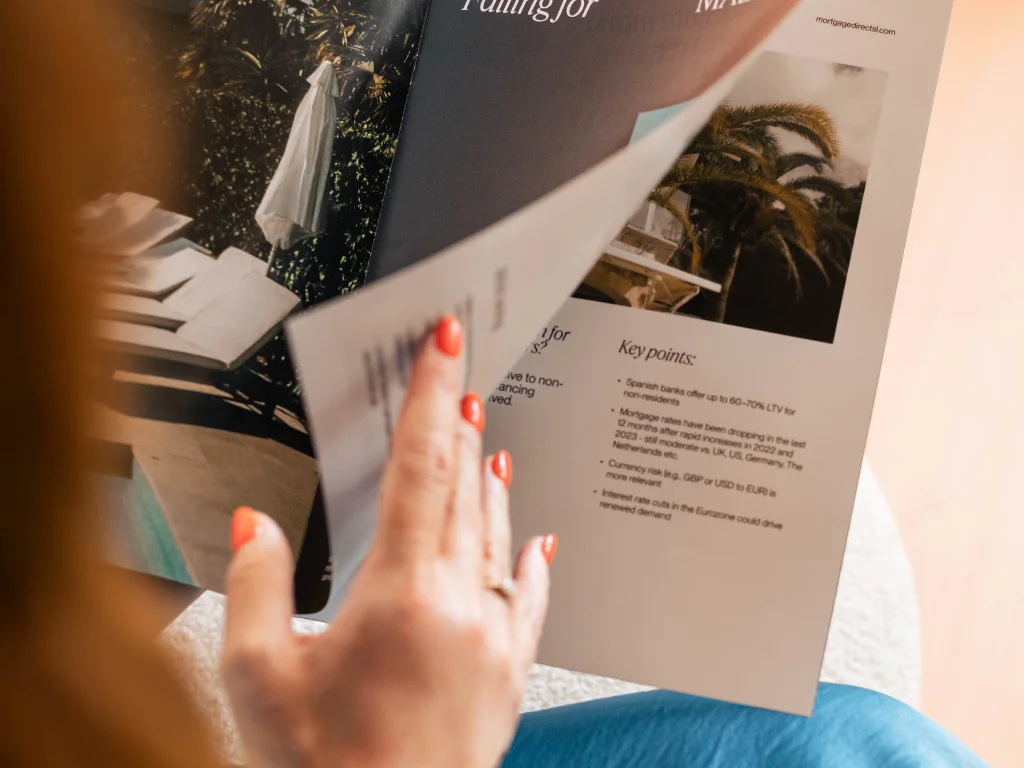
Spanish lenders generally apply more conservative lending criteria to non-resident buyers than to Spanish residents. Depending on the lender, the property and the borrower’s overall financial profile, financing of 60% to 70% of the property’s value is common.
This means buyers should normally expect to contribute 30% to 40% of the purchase price from their own funds. However, that is only the beginning of the calculation.
The deposit does not include acquisition costs
A mortgage finances part of the purchase price.
It does not normally finance the costs associated with acquiring the property.
These may include:
- Property Transfer Tax (ITP) or VAT (IVA)
- Stamp Duty (where applicable)
- Legal fees
- Notary fees
- Land Registry fees
- Property valuation costs
- Technical due diligence
- Other transaction expenses
Depending on the type of property and its location, buyers often allow approximately 12% to 15% of the purchase price to cover these additional costs.
As a result, a buyer receiving 70% financing should typically expect to have total available liquidity of approximately 42% to 45% of the purchase price.
Where financing is closer to 60%, the overall capital requirement may increase to 52% to 55%.
Acquisition taxes depend on the property and the region
A common misconception is that property taxes are the same throughout Spain.
They are not.
For resale properties, buyers generally pay Property Transfer Tax (ITP). The applicable rate varies between Spain’s autonomous regions and, in some regions, the tax is calculated using progressive bands, meaning the effective rate may increase as the purchase price rises.
For new-build properties purchased directly from a developer, buyers generally pay 10% VAT (IVA) instead of transfer tax. Depending on the transaction, Stamp Duty (AJD) may also apply.
These differences can have a material impact on the total capital required to complete a purchase, particularly for higher-value properties.
The bank's valuation can change the numbers
Another important consideration is that lenders do not necessarily calculate the mortgage using the agreed purchase price. Instead, they rely on an independent valuation of the property. If that valuation is lower than the agreed purchase price, the lender will normally calculate the maximum mortgage against the lower value.
For example, a buyer may agree to purchase a property for €2 million, expecting to borrow 70%.
If the independent valuation is €1.85 million, the maximum mortgage may be calculated on that lower figure, increasing the buyer’s own contribution significantly. For prime properties, where negotiated purchase prices and valuations do not always align, this can be a more important consideration than the advertised loan-to-value ratio itself.
Every lender assesses international buyers differently
There is no standard mortgage policy for non-residents.
Each lender applies its own underwriting criteria and assesses risk differently.
Factors typically include:
- Country of residence
- Source of income
- Currency in which income is received
- Employment or business structure
- Existing assets and liabilities
- Property type and location
- Loan size
- Overall client profile
As a result, two buyers purchasing similar properties may receive very different financing proposals.
Selecting the right lender is therefore often just as important as negotiating the mortgage itself.
Purchasing through a company requires different planning
Not every property in Spain is acquired in a personal name.
For investment or succession planning purposes, some buyers choose to purchase through a corporate structure.
In these situations, the financing can differ materially from a standard residential mortgage.
For example, mortgage-related taxes that are typically borne by the lender in a consumer mortgage may, depending on the structure and nature of the transaction, become payable by the purchaser.
Corporate acquisitions therefore require close coordination between legal, tax and financing advisers before any commitments are made.
High-net-worth clients are not always assessed on income alone
Many private clients have substantial wealth but relatively modest taxable income.
Entrepreneurs, business owners, investors and internationally mobile families often structure their affairs differently from salaried employees. Traditional affordability models do not always reflect their overall financial strength.
This is where lender selection becomes particularly important.
Certain lenders are able to assess a client’s wider financial position rather than relying solely on annual taxable income.
Where a broader private banking relationship forms part of the financing strategy, additional flexibility may be available. Depending on the overall relationship, investment assets held with the bank and the client’s balance sheet, financing can sometimes exceed the loan-to-value ratios typically available through mainstream retail lending.
The objective is not necessarily to maximise borrowing, but to structure the financing in a way that supports the client’s broader wealth strategy.
Think in terms of liquidity, not simply the deposit
Before committing to a purchase, we encourage clients to establish three figures:
- the likely mortgage available for their personal circumstances;
- the total acquisition costs associated with the purchase;
- the amount of liquidity they wish to preserve after completion.
These questions often prove far more valuable than focusing solely on the maximum loan-to-value ratio.
Our perspective
For most international buyers, the commonly quoted 30% deposit is only part of the story.
A more realistic planning assumption is often:
- 30% to 40% of the purchase price as the buyer’s own equity contribution;
- plus approximately 12% to 15% for taxes and transaction costs;
- plus an appropriate contingency should the bank’s valuation differ from the agreed purchase price.
More importantly, these calculations should be completed before signing a reservation agreement or private purchase contract.
Understanding your borrowing capacity, the likely valuation outcome and your true capital requirement provides certainty, strengthens your negotiating position and helps avoid unexpected funding gaps later in the transaction.
Because successful property finance is not simply about securing a mortgage.
It is about ensuring that the financing complements your wider financial strategy while preserving the flexibility to achieve your long-term objectives.